Enter your limited company’s taxable profit to work out its Corporation Tax bill for 2026/27.
The calculator accounts for the 19% and 25% rates and marginal relief, and shows how much taxable profit remains after Corporation Tax.
Corporation Tax Calculator
UK limited companies – 2026/27
Corporation Tax rates for 2026/27
For a fuller explanation of how the tax works, including CT600 returns and payment deadlines, see our Corporation Tax guide for small companies.
The small profits rate is 19% on taxable profits up to £50,000. Once profits reach £250,000, the rate is 25%. Companies between those figures may qualify for marginal relief, so their effective rate is somewhere between 19% and 25%.
These are the rates for the financial year from 1 April 2026 to 31 March 2027. The £50,000 and £250,000 thresholds can be lower if you have associated companies or a short accounting period. See HMRC’s Corporation Tax rates.
How marginal relief works
You don’t suddenly pay 25% on everything when profits go above £50,000. Marginal relief reduces the bill between the two thresholds.
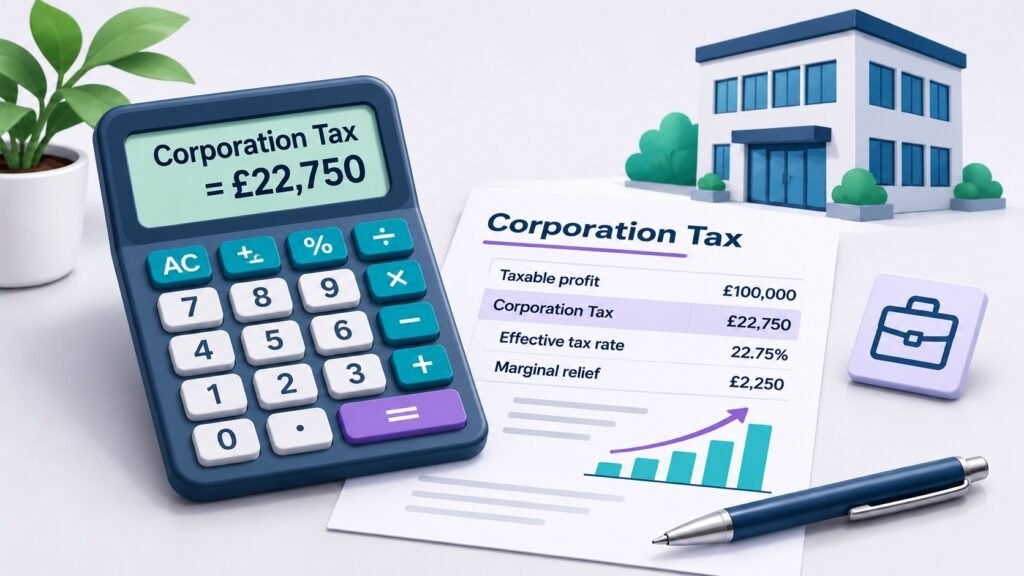
For example, a company with £100,000 in taxable profits, a full accounting year and no associated companies pays £22,750 in Corporation Tax. That’s an effective rate of 22.75%. HMRC explains the calculation in its marginal relief guidance.
Which profit figure should you enter?
Use the company’s taxable profit, not turnover or the balance in its bank account. That’s the profit after allowable expenses and any relevant tax adjustments. If you’re unsure what can be deducted, see our guide to limited company expenses.
For a wider calculation that includes a director’s salary and dividends, try the Limited Company Tax Calculator.
If you have more than one company
The profit thresholds are shared between associated companies. If you have one other associated company, for example, the £50,000 and £250,000 limits are normally halved to £25,000 and £125,000.
You can enter the number of other associated companies under Advanced options. Don’t count the company you’re calculating tax for. The rules depend on who controls the businesses, and some dormant companies are ignored. See HMRC’s guidance if you’re not sure.
When the calculation may be different
The calculator assumes a UK trading company with a 12-month accounting period covered by the 2026/27 rates. If your accounts cover a shorter period, cross financial years or include certain exempt distributions, the tax calculation may differ.
It also doesn’t deal with losses, R&D relief, group relief, investment holding companies, ring fence profits or Corporation Tax payment deadlines. Your accountant or tax software should handle those cases.
The amount left after Corporation Tax is based on taxable profit. It isn’t necessarily your accounting profit after tax, or the amount available to pay out as dividends. See our guide to salary and dividends for directors if you’re deciding how to take money out of the company.